



Instalment payments and savings goals in Nigeria belong in the same budget calendar. A payment can fit this month while leaving too little for a planned goal or a cash buffer. Equally, paying upfront can reduce liquidity at the wrong time. Compare the complete schedules rather than choosing from the size of one payment.
A new research paper gives this question a timely starting point. Our article separates its experimental findings from an original fictional naira calendar. Two charts, a comparison infographic and four CSV downloads help you keep payment obligations and other goals visible together.
What the instalment research measured
The 11 November 2026 Marketing Letters paper by Jiabi Wang, Daniel Katz, Christina Kan and Abigail Sussman reports four preregistered studies. They use compressed hypothetical payment scenarios. They are not longitudinal observations of Nigerian household finances, and the mock-calendar months are not fieldwork dates.
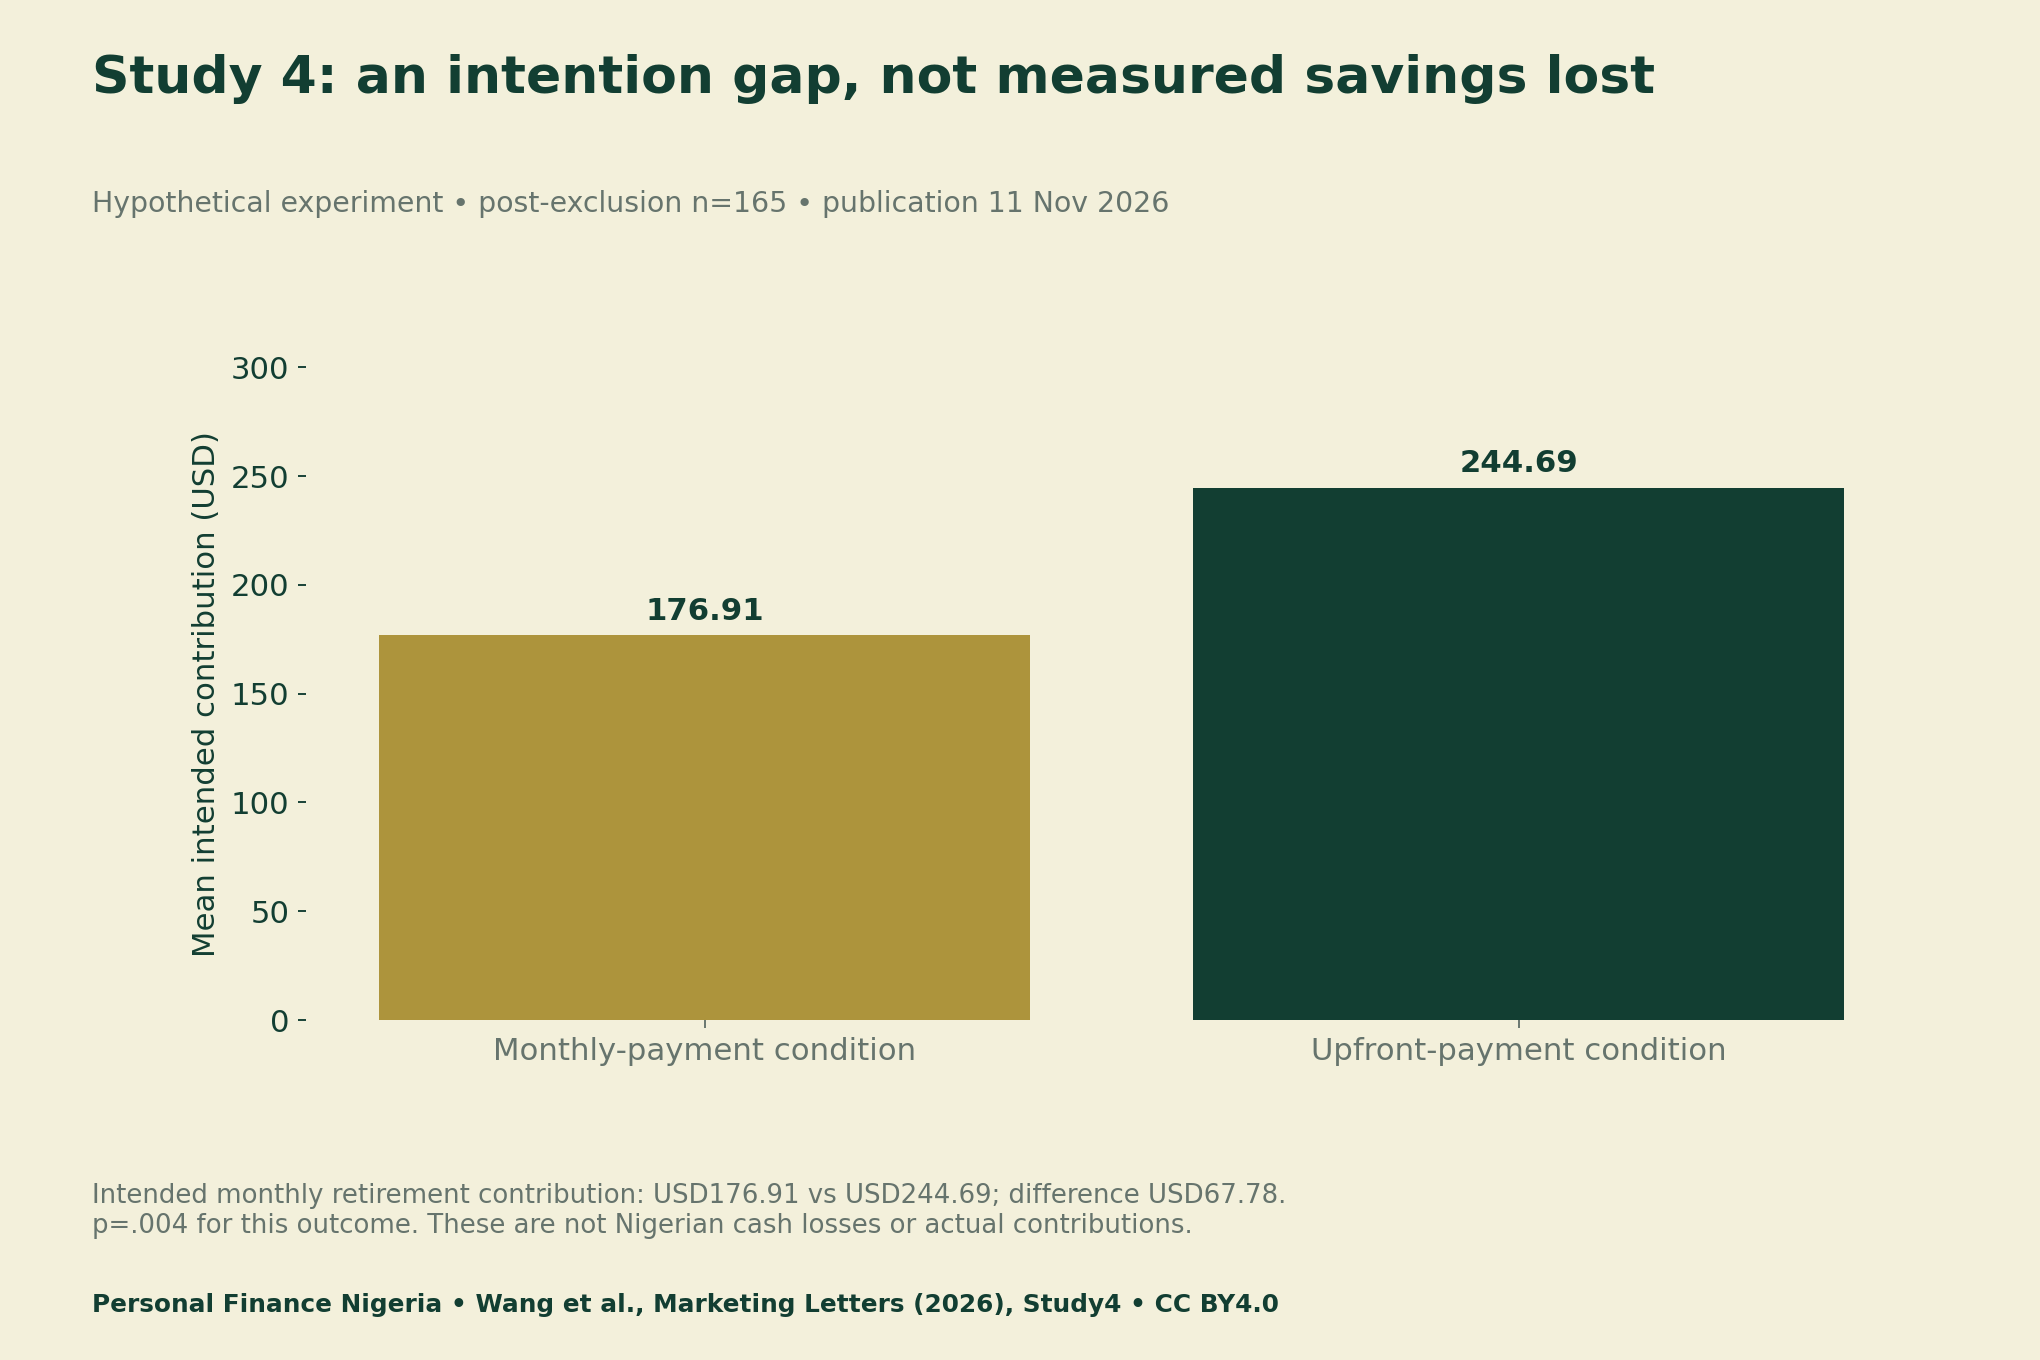
Study 4’s reported contribution gap was $67.78. Its separate perceived-constraint comparison had p=.055, which does not meet a conventional 5% threshold. Do not turn the contribution difference into a naira loss, predict a Nigerian effect size or describe every study outcome as statistically significant.
The paper links authors’ materials and data on OSF. That repository was not accessible during this preparation, so this article does not claim an independent reanalysis. The selected result is checked against the published paper; the practical worksheet is our own planning framework, not a tested intervention.
Instalment payments and savings goals need two records
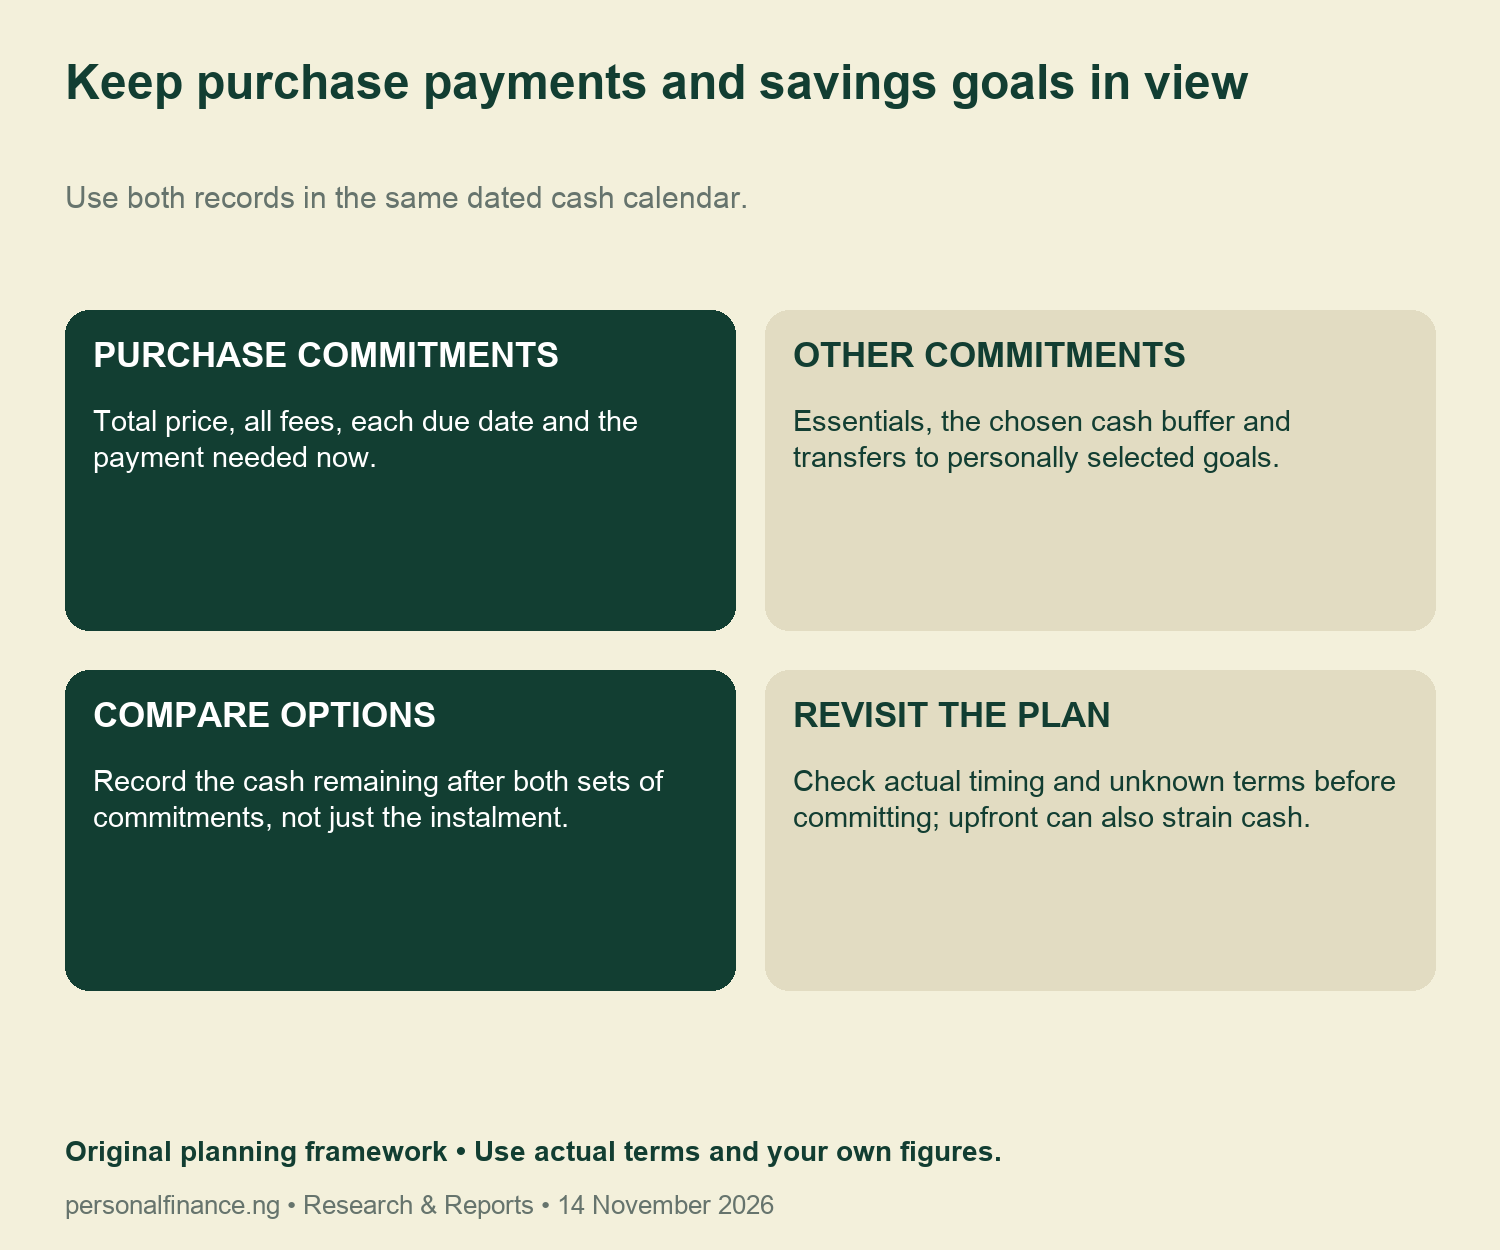
First list what the purchase requires: money due now, every later payment, mandatory fees and the final total. Second list the commitments that remain important without the purchase. Include essentials, your selected buffer and transfers to goals such as school fees or emergency savings.
Give both records dates. A monthly total can hide a payment due before income arrives. If a goal transfer is flexible, state the change you would be making instead of quietly removing it. That makes the trade-off visible before the commitment is made.
A fictional six-month comparison
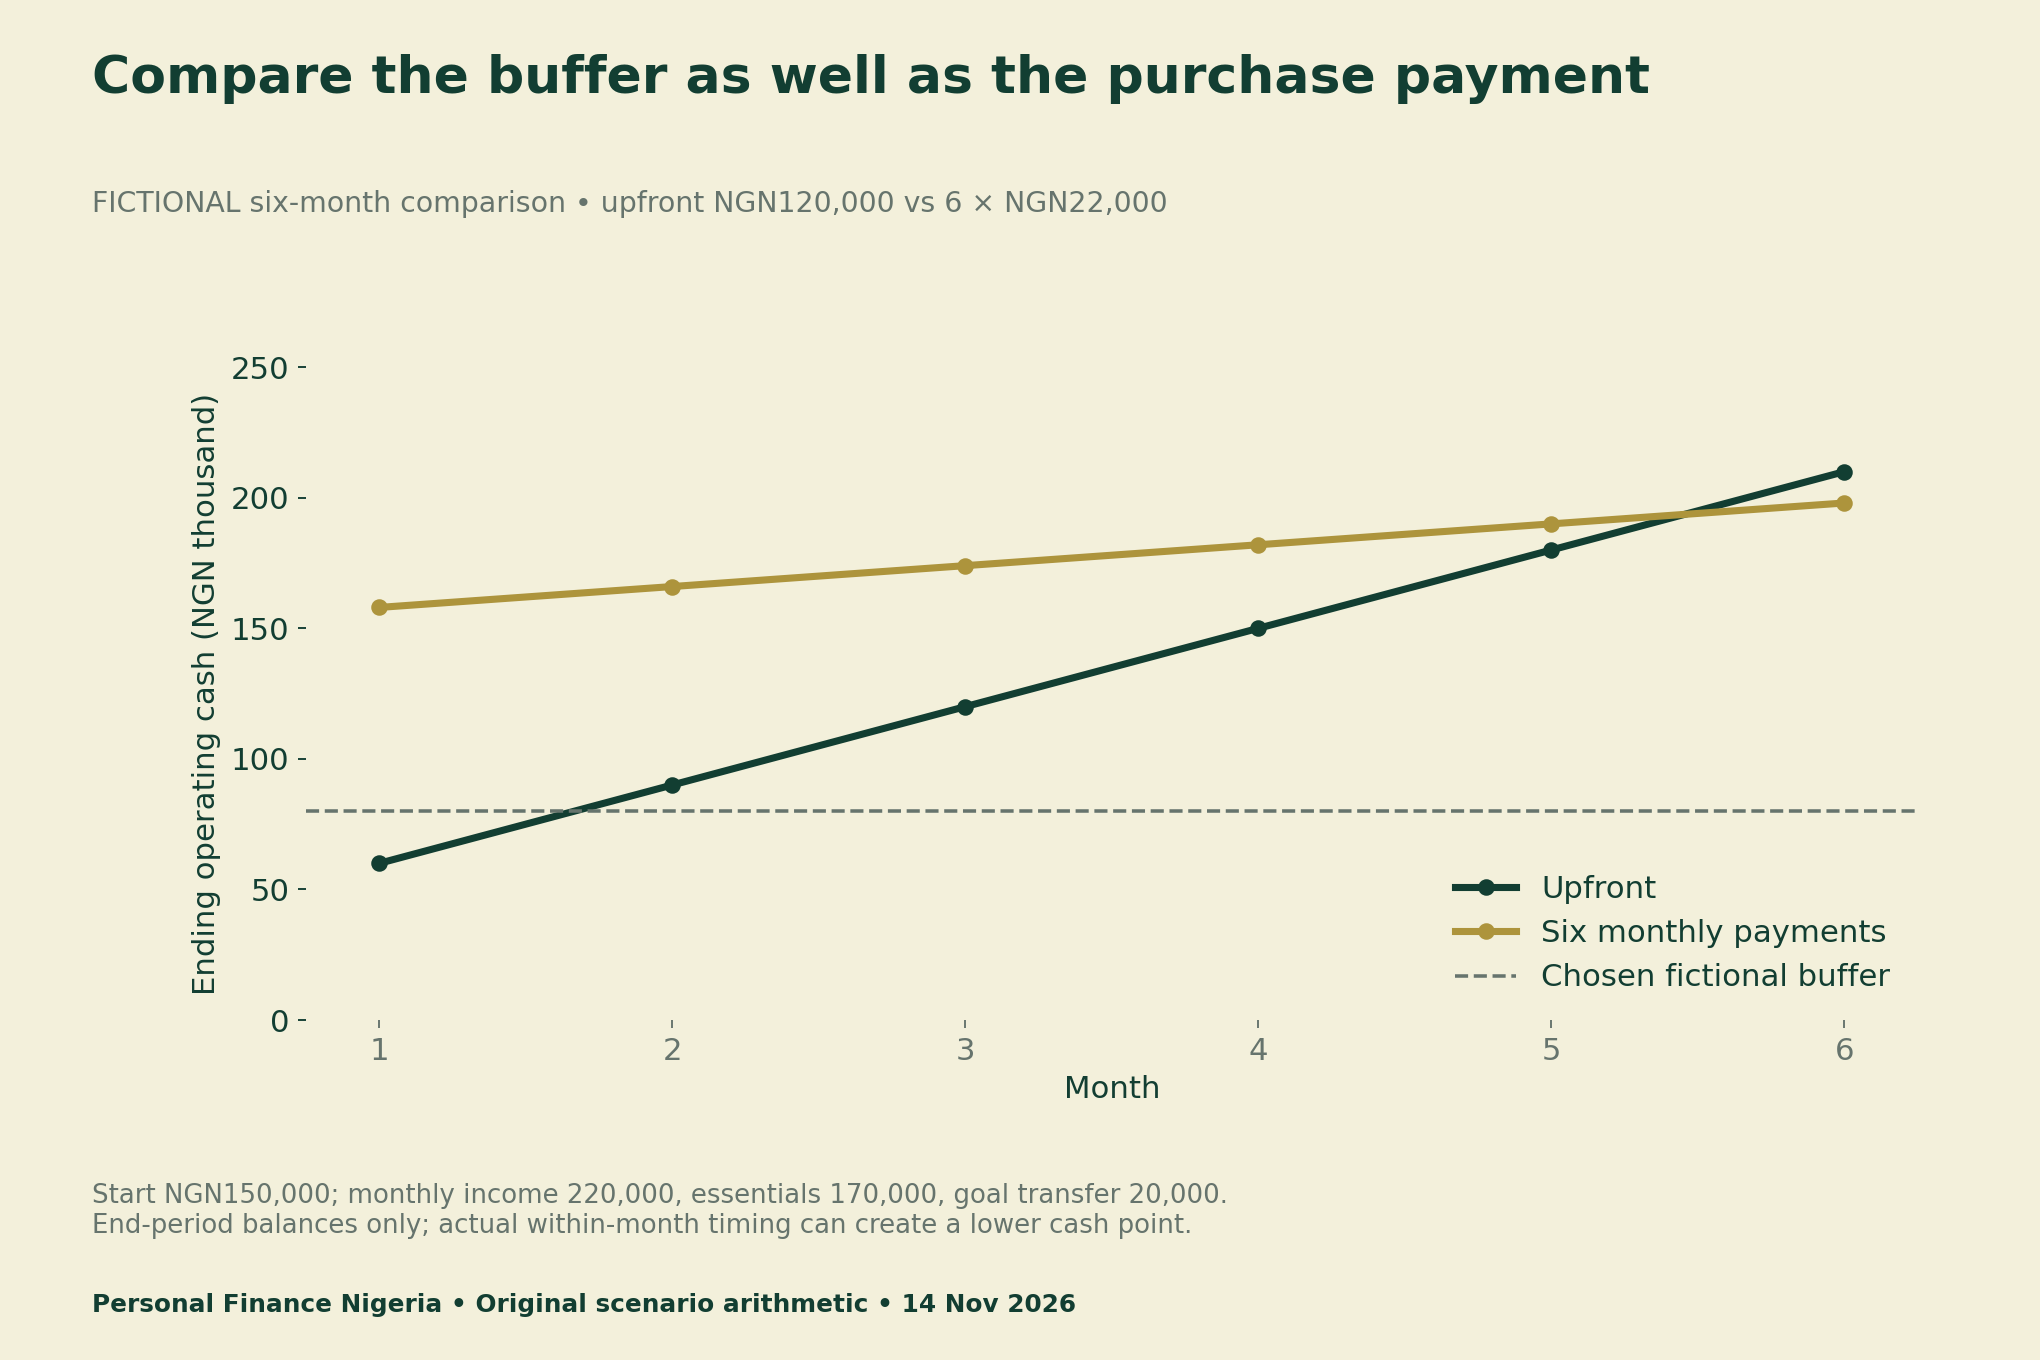
Our example starts with ₦150,000 operating cash. Each month brings ₦220,000 income, ₦170,000 essential outgoings and a ₦20,000 transfer to a separate savings goal. That leaves ₦30,000 before the purchase payment. The chosen operating-cash buffer is ₦80,000; it is an illustrative input, not a recommended amount.
The upfront option costs ₦120,000 in month one. The instalment option costs six payments of ₦22,000, or ₦132,000 in total. The ₦12,000 difference is simply the assumed difference between these fictional options; it is not an annual rate or a verified offer from a lender.
| Comparison | Upfront option | Six-payment option |
|---|---|---|
| Total purchase payments | ₦120,000 | ₦132,000 |
| Month-one ending operating cash | ₦60,000 | ₦158,000 |
| Month-six ending operating cash | ₦210,000 | ₦198,000 |
| Savings-goal transfers over six months | ₦120,000 | ₦120,000 |
The upfront choice ends month one below the example’s buffer, while the instalment option preserves more operating cash then. By month six, the upfront option leaves more operating cash because its total cost is lower. Those findings describe these inputs, not a universal ranking of payment formats.
Check timing before relying on the ending balance
The chart shows end-period balances. If a purchase is due before the month’s income arrives, cash could fall below the displayed figure during the month. Put the actual receipt and due dates in your own calendar. A positive month-end figure is not proof that every earlier payment can be met.
Keep savings transfers distinct from spending. In this example they leave the operating account but remain in a separate goal account. Combining the accounts for a total-asset question requires that transfer to be removed from expenses, so it is not treated as money destroyed.
Questions that keep the goal visible
Which goal transfer would still happen under each option? What cash remains after essentials and every payment due before the next reliable receipt? Would a smaller or deferred purchase avoid sacrificing the goal? Which fee or date is still unknown? Answer with actual figures instead of the advertised instalment alone.
Do not assume the lowest total cost always solves the cash problem, or that a smaller payment always makes a purchase manageable. The comparison needs both timing and cost. If the plan only works by removing an important goal transfer, record that decision explicitly and revisit the purchase itself.
Compare instalment payments and savings goals with four tools
- Published Study 4 selected-result register (CSV)
- Fictional six-month cash and goal calendar (CSV)
- Blank payment-option comparison sheet (CSV)
- Blank savings-goal attention checklist (CSV)
For a separate accounting question, our revolving-credit ledger explains why a restored borrowing limit is not new income. The auction-cost worksheet keeps purchase costs outside the bid visible.
Your Personalized Financial Plan
Get expert financial advice tailored exclusively to your goals. Receive a custom roadmap in just 1-3 business days.
Get StartedMethods and limits
Research checked on 14 November 2026. We redrew the selected published means and calculated their difference without adding unreported uncertainty estimates. We did not reproduce the authors’ raw-data analysis. The six-month naira calendar is an independent fictional example, with constant income, essential outgoings and goal transfers; no research effect size is used in it.
The paper’s hypothetical design does not establish actual long-term savings outcomes or direct transfer to Nigeria. The worksheet has not been validated as a behavioural intervention. Suggested citation: Personal Finance Nigeria, “Paying in Instalments: Protect Savings Goals as Well as Monthly Bills”, original calendar and tools; cite Wang et al. separately for the research findings.


