When Higher Income Creates Constant Pressure
Lifestyle inflation occurs when spending rises alongside income.
As earnings increase, people may expand their lifestyles instead of strengthening their financial position.
Consequently, higher income can provide little relief from ongoing financial pressure.
How Spending Expands
Greater income can make more expensive choices feel manageable.
However, repeated upgrades can gradually increase monthly financial commitments.
Each new commitment may reduce the flexibility that rising income should provide.
Therefore, earning more does not automatically create greater financial stability.
Why Financial Pressure Persists
Lifestyle inflation can absorb additional income before it creates meaningful financial space.
When spending continually grows, financial demands may remain high despite better earnings.
As a result, people can feel pressure to maintain their expanded lifestyles.
This pressure can make changes feel difficult when income or priorities shift.
The Cost of Larger Commitments
Higher spending often creates obligations that continue beyond a single purchase.
Those obligations can limit choices and keep future income assigned to current expenses.
Meanwhile, rising costs can make an expanded lifestyle increasingly difficult to sustain.
Financial pressure grows when commitments leave little room for changing circumstances.
Your Personalized Financial Plan
Get expert financial advice tailored exclusively to your goals. Receive a custom roadmap in just 1-3 business days.
Get StartedRecognizing Lifestyle Inflation
Notice whether each income increase leads to higher ongoing spending.
Also, consider whether additional earnings create flexibility or simply support new commitments.
If financial pressure remains constant, lifestyle growth may absorb the added income.
Recognizing this pattern creates an opportunity to reassess spending decisions.
Creating Room Instead of Pressure
Keeping lifestyle growth intentional can help preserve the benefits of higher earnings.
Instead of expanding every expense, direct attention toward maintaining financial flexibility.
This approach helps income support choices rather than creating constant pressure.
Ultimately, rising earnings offer greater value when spending does not rise automatically.
The Hidden Cost of Borrowed Spending
Funding an expensive lifestyle can create costs beyond the original purchase.
Credit, loans, and unpaid bills can turn today’s spending into tomorrow’s obligation.
Therefore, borrowed spending can reduce the money available for current needs.
More Than the Original Price
Credit may increase the total amount required to repay a purchase.
Loans can also extend the financial impact of one spending decision.
Meanwhile, unpaid bills can remain obligations after the original service or purchase ends.
Unlock a Debt-Free Future with Our Unique Strategies
Imagine a life unburdened by debt—a reality we help you visualize and achieve. We offer personalized strategies tailored to your unique situation, guiding you step-by-step toward financial freedom.
Start TodayAs a result, the final cost may exceed the amount initially expected.
Less Freedom With Future Income
Repayment commitments claim part of future income before new choices arise.
Consequently, fewer funds remain available for changing priorities.
These obligations can make ordinary financial decisions feel more restricted.
They can also limit the ability to respond comfortably when expenses change.
The Pressure of Unpaid Bills
Unpaid bills can create continuing pressure because the obligation remains unresolved.
Each delayed payment can add another concern to an already demanding financial situation.
Furthermore, unpaid balances can compete with essential spending and other responsibilities.
Addressing them requires attention that could otherwise support more flexible choices.
When Payments Compete
Multiple obligations can compete for the same available income.
Credit payments, loan payments, and unpaid bills may all demand attention simultaneously.
Therefore, one expensive choice can affect several later decisions.
This competition can make spending feel less manageable, even when income continues.
Recognizing the Real Cost
Responsible spending requires considering repayment, not only immediate access.
Unlock Untapped Nigerian Wealth with Our Expert Advice
Imagine accessing investment opportunities others overlook—stocks, bonds, real estate, small businesses tailored to you. We offer personalized advice you won't find elsewhere, guiding you to financial success.
Unlock WealthBefore using credit or loans, consider how the obligation affects future income.
Also, examine whether unpaid bills could create additional pressure later.
Ultimately, the real cost includes the financial flexibility sacrificed afterward.
Emergency Savings Remain Out of Reach
Living above your means leaves less money available for emergency savings.
As a result, unexpected costs can disrupt your progress toward financial stability.
Without dedicated savings, each financial surprise may compete with regular priorities.
Therefore, high spending can delay the creation of a reliable financial cushion.
Investing Starts Later
Investing requires money that remains available after necessary spending.
When discretionary costs consume that money, investing receives less funding and attention.
Consequently, delayed investing can postpone progress toward long-term financial goals.
Even when income increases, higher spending can continue limiting available investment money.
Reducing excess expenses creates more room to begin or increase investing.
Long-Term Goals Lose Momentum
Financial goals depend on consistent progress over time.
Excess spending reduces the money available for priorities beyond the present.
Those priorities may include emergency savings, investing, and other long-term plans.
Furthermore, competing expenses can force you to place important goals on hold.
Each delay makes it harder to maintain steady progress toward those goals.
Redirecting Money Toward Priorities
Reviewing spending helps identify money that could support future priorities.
Next, assign available money to emergency savings, investing, or other goals.
This approach gives each dollar a clearer purpose.
It also helps separate immediate wants from long-term financial needs.
As spending becomes more intentional, financial goals can receive consistent support.
Gain More Insights: Why Accountability Matters More Than Budgeting Apps
When Financial Overextension Reaches Beyond Money
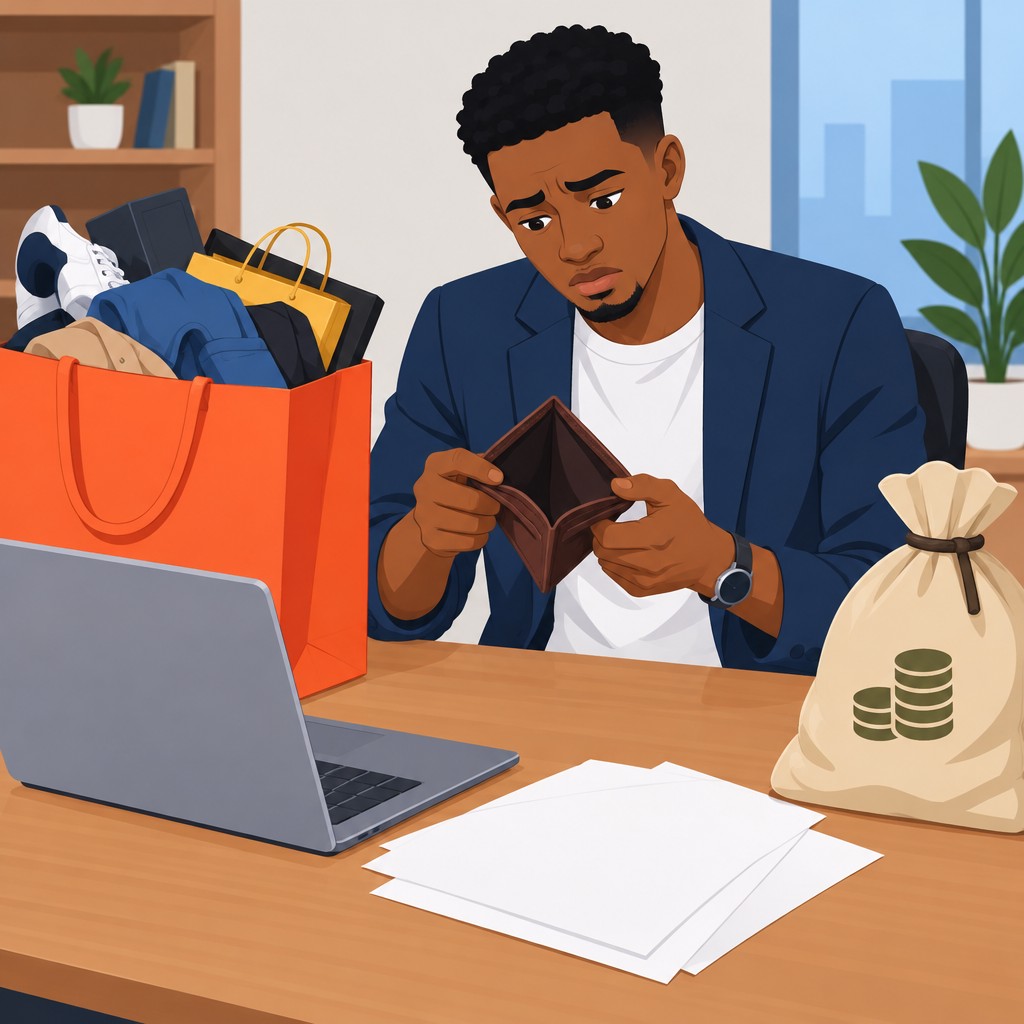
Financial overextension can affect more than a person’s available money.
It can influence emotions, relationships, personal freedom, and everyday decisions.
Recognizing these effects can encourage more sustainable financial choices.
Emotional Strain
Financial overextension can create persistent pressure during an important stage of life.
Each spending decision may feel heavier when available money remains limited.
Moreover, financial concerns can occupy attention that supports rest, focus, and personal wellbeing.
Uncertainty can also make ordinary choices feel difficult.
As pressure continues, people may experience frustration, embarrassment, or a reduced sense of control.
Recognizing these emotional effects reveals the broader cost of unsustainable spending.
Pressure Within Relationships
Money pressure can affect communication between partners, relatives, friends, or housemates.
Different spending expectations may create tension when people share responsibilities or make plans together.
Furthermore, financial stress can encourage avoidance instead of honest conversations.
Silence may leave others uncertain about priorities, boundaries, or available support.
Open communication can clarify expectations before financial pressure damages trust.
People can discuss spending limits, shared obligations, and personal needs directly.
Although these conversations may feel uncomfortable, they can reduce confusion and resentment.
Reduced Personal Freedom
Living above your means can limit your ability to respond to changing priorities.
Financial commitments may influence decisions about work, housing, relationships, and daily activities.
Consequently, a lifestyle that appears comfortable can restrict meaningful choices.
People may decline opportunities because their current spending leaves little flexibility.
They may also remain in unwanted situations because changing direction feels financially difficult.
Therefore, overextension affects freedom, not merely purchasing power.
Restoring Room to Choose
Creating more financial space can support clearer decisions and calmer relationships.
First, identify which commitments create the greatest ongoing pressure.
Then, consider how those commitments affect wellbeing, communication, and personal choices.
Next, discuss shared financial expectations with the people involved.
Finally, protect decisions that increase flexibility rather than preserving appearances.
Small changes can gradually restore a stronger sense of control.
See Related Content: Why Paying Off Debt Is More Psychological Than Mathematical
When Appearance Shapes Spending
Status-driven spending focuses on how purchases appear to other people.
Consequently, public presentation can become more important than private affordability.
Furthermore, public presentation can influence spending priorities.
The Public Image
A carefully maintained image may suggest financial comfort.
However, that image often reveals only selected parts of someone’s financial life.
People may display expensive choices while keeping financial limitations private.
Therefore, observers can mistake appearance for genuine financial stability.
The Private Financial Gap
Status spending creates a gap when outward choices exceed available financial capacity.
This gap separates what someone wants others to believe from what their finances support.
Meanwhile, maintaining appearances can require repeated spending decisions.
Each decision may feel necessary when status influences personal expectations.
Over time, those expectations can shape spending more strongly than practical priorities.
How Social Pressure Reinforces the Pattern
Social settings can encourage people to match visible standards.
Moreover, comparison can make ordinary choices feel insufficient.
When status becomes the measure of success, restraint may appear less acceptable.
As a result, people may protect an image instead of acknowledging financial limits.
Recognizing the Mismatch
Awareness begins by comparing public choices with private financial capacity.
First, identify spending decisions that primarily support appearance.
Next, consider whether each decision reflects personal priorities or social expectations.
Then, notice whether the desired image requires ongoing financial compromise.
This review can reveal where presentation has replaced affordability.
Rebuilding Authentic Priorities
A more sustainable approach aligns visible choices with private financial reality.
Instead of performing status, people can define success through personal values.
Additionally, honest priorities reduce the pressure to maintain an unrealistic image.
Ultimately, financial confidence grows when public presentation no longer depends on overspending.
Uncover the Details: The Invisible Debt That Comes From Borrowing Peace of Mind
Career Risks of an Expensive Lifestyle
An expensive lifestyle can make career decisions depend more on monthly obligations than professional direction.
High expenses can limit flexibility when income remains unstable.
As a result, financial commitments may influence career choices before professional stability develops.
Reduced Freedom to Change Roles
When income remains unstable, high expenses can make a job change feel financially impossible.
Consequently, you may stay in a role that no longer supports your development.
You might also reject opportunities that offer valuable experience but provide less immediate income.
Therefore, lifestyle commitments can narrow your choices before your career gains stability.
Pressure to Prioritize Immediate Income
Expensive obligations can encourage you to choose short-term pay over long-term career growth.
However, immediate income may not always align with your skills, interests, or professional goals.
This pressure can discourage thoughtful decisions about training, responsibilities, or future opportunities.
As a result, your lifestyle may begin directing your career instead of supporting it.
Limited Room for Professional Development
Career development often requires time, attention, and flexibility.
Yet, costly commitments can limit your ability to pursue learning or accept changing responsibilities.
You may avoid unpaid preparation, reduced hours, or transitional work when expenses demand steady earnings.
Thus, financial dependence on one income level can restrict your professional options.
Greater Vulnerability During Employment Changes
Employment changes can create uncertainty before your income becomes consistent.
Meanwhile, an expensive lifestyle continues demanding regular financial support.
This mismatch can force rushed career decisions during periods of transition.
For example, you may accept unsuitable work simply because your expenses leave little flexibility.
Maintaining lower fixed costs can give your career more space to develop deliberately.
Strained Professional Boundaries
Financial dependence can make it harder to set healthy boundaries at work.
You may accept excessive demands because losing income feels too risky.
Over time, this pattern can influence which responsibilities you tolerate and which opportunities you pursue.
Therefore, controlling lifestyle costs can protect your ability to make career decisions with greater independence.
Discover More: How Credit Really Works and Why It’s Not Free Money
Warning Signs Your Spending Has Outgrown Your Income
Your spending may exceed sustainable income before the problem becomes obvious.
Therefore, watch for patterns that show your budget lacks enough breathing room.
These patterns can help you reassess spending before financial pressure grows.
Your Money Runs Out Before the Month Ends
If your income disappears early, regular spending may exceed your available resources.
Moreover, repeated shortfalls suggest that your routine depends on perfect timing.
A sustainable budget should support ordinary needs throughout the entire month.
Essential Costs Leave Little Flexibility
Notice whether essential expenses consume most of your available income.
When necessities leave little flexibility, small changes can disrupt your plans.
Consequently, your lifestyle may require more income than your finances reliably provide.
You Depend on Future Income
Another warning sign appears when you spend money before receiving your next income.
This pattern can make each pay period feel committed before it begins.
As a result, your choices become narrower and your financial margin continues shrinking.
You Delay Necessary Decisions
You may recognize a problem when you repeatedly postpone reviewing your spending.
For example, you might avoid checking balances or assessing recurring commitments.
However, avoiding information does not reduce the pressure those commitments create.
Regularly delaying decisions can indicate that your lifestyle no longer feels manageable.
Your Spending Requires Constant Justification
Frequent explanations can signal that your purchases do not match your available income.
You might defend spending decisions instead of evaluating their effect on your budget.
Similarly, comparing yourself with others can distract you from your financial capacity.
A sustainable lifestyle should fit your income without requiring constant defense.
You Cannot Adjust When Circumstances Change
Test your budget by considering whether you could reduce spending when circumstances change.
If every category feels fixed, your lifestyle may contain too many commitments.
Furthermore, limited flexibility can prevent calm responses to ordinary uncertainty.
Your spending should leave room for deliberate adjustments when priorities shift.
Your Priorities Keep Moving Further Away
Review whether your current spending supports the priorities you value most.
If daily purchases repeatedly crowd out those priorities, your lifestyle may lack direction.
Over time, this mismatch can weaken your progress toward meaningful goals.
Therefore, compare your spending choices with the goals you intend to support.
A Simple Warning-Sign Review
Consider these questions when assessing whether your spending remains sustainable.
Does your income cover regular needs without creating end-of-month pressure?
Can you adjust discretionary spending without disrupting essential commitments?
Do your current choices support your most important financial priorities?
Can you review your spending honestly without avoiding uncomfortable information?
If several answers concern you, your spending may require closer attention.
Recognizing these signs early gives you an opportunity to reassess your lifestyle deliberately.
A Practical Financial Reset
A financial reset begins with clear decisions about spending, debt, and stability.
Start by replacing vague concern with a simple review.
Use that review to understand your current money habits.
Pausing Nonessential Spending
First, pause purchases that do not support immediate needs or financial recovery.
This pause creates room to evaluate expenses without adding new pressure.
Meanwhile, keep essential spending separate from optional spending during this review.
Then, delay nonessential commitments until your finances feel more manageable.
Building a Clear Spending Picture
Review recent spending and group each expense by purpose.
Separate necessities, obligations, convenience purchases, and discretionary spending.
Next, compare total expenses with the income available for those expenses.
Also, mark recurring charges that no longer support your current priorities.
Cancel or reduce expenses only after confirming their importance and timing.
Ultimately, a clear spending picture helps direct money toward immediate responsibilities.
Creating a Lean Spending Plan
Design a spending plan around essential costs, debt payments, and basic financial needs.
Before spending begins, give every available amount a defined purpose.
Protect essential obligations first, then assign remaining money toward debt reduction.
Additionally, keep the plan realistic enough to follow during ordinary weeks.
A practical plan should guide decisions without requiring perfect behavior.
Organizing Debt Responsibilities
List each debt, its required payment, and its current status.
Keep payment information together so you can review obligations consistently.
Prioritize required payments before directing extra money toward balances.
Next, choose a repayment order that feels clear and sustainable.
Send additional available money toward one selected balance.
Meanwhile, maintain all other required payments.
As one obligation changes, update the plan instead of relying on memory.
Addressing Payment Pressure Early
Contact creditors or service providers when payment difficulties appear.
Explain your situation clearly and ask which arrangements may reduce immediate pressure.
Review any proposed arrangement before accepting new terms.
Keep records of agreements, payment dates, and follow-up responsibilities.
Consequently, early communication can help you manage obligations more deliberately.
Separating Needs From Convenience
Ask whether each purchase solves a need or maintains a preferred routine.
When possible, replace expensive convenience with simpler choices.
Before buying, check whether the expense fits your current spending plan.
Additionally, use a waiting period for purchases that feel urgent but remain optional.
This approach creates space between desire and action.
Rebuilding Financial Stability
After essential payments receive attention, direct available money toward a basic cash reserve.
Keep this reserve separate from everyday spending.
Furthermore, replenish the reserve whenever unexpected spending reduces it.
Resume longer-term goals only after immediate obligations receive consistent attention.
Ultimately, stability grows when your plan protects present needs and future flexibility.
Making Progress Visible
Review your spending plan and debt balances regularly.
Track completed payments and reduced expenses without judging past decisions.
Use each review to identify one adjustment that supports your priorities.
Celebrate consistency through evidence rather than increased spending.
As a result, visible progress can strengthen your commitment to the reset.
Preventing a Return to Overextension
Set personal rules for discretionary spending before temptation appears.
Keep new commitments aligned with dependable income rather than optimistic expectations.
Recheck recurring expenses whenever your circumstances change.
Discuss major financial decisions with anyone sharing household spending responsibility.
Finally, treat financial stability as an ongoing practice instead of a single correction.
Additional Resources
Google search results for The Price of Living Above Your Means in Your Twenties Debt Management
Bing search results for The Price of Living Above Your Means in Your Twenties Debt Management