How Risk Pooling Works
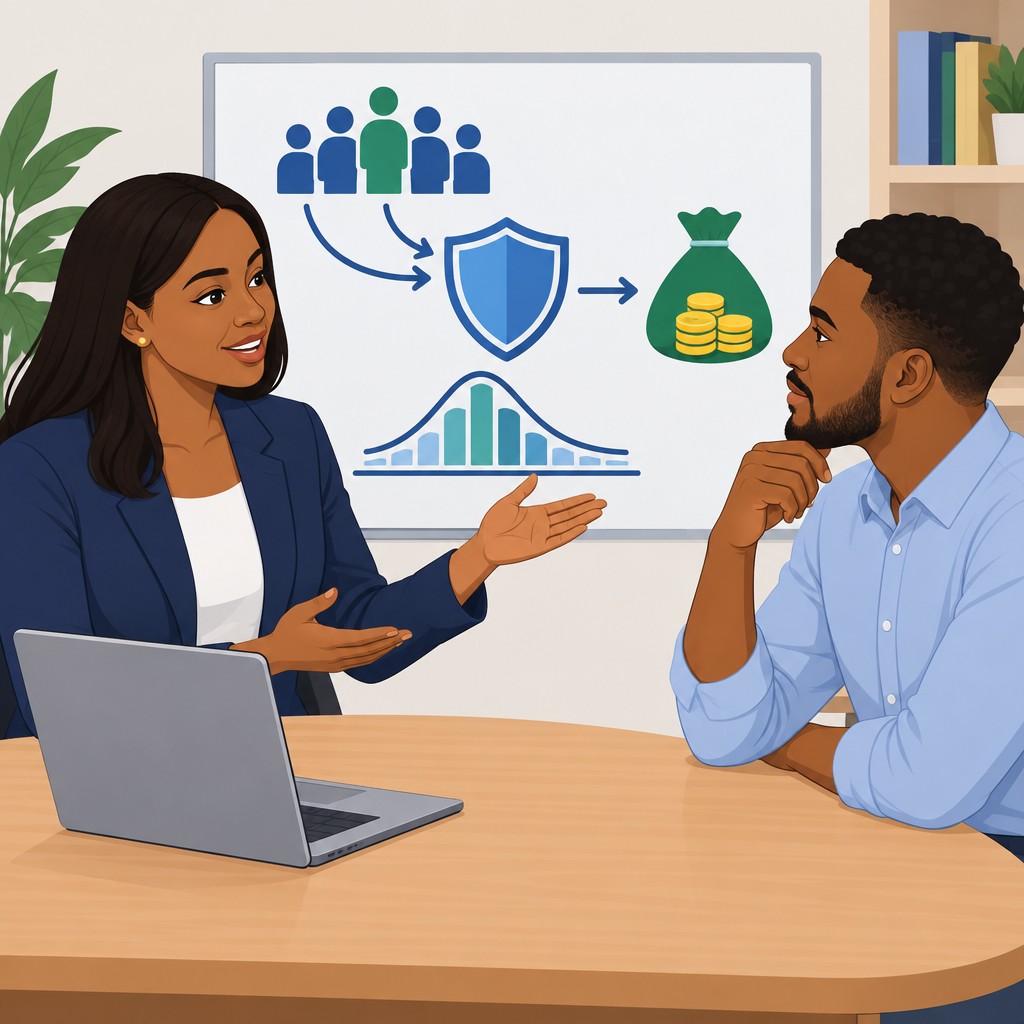
Insurance uses risk pooling to spread financial risk across many policyholders.
Each policyholder contributes through premium payments.
Meanwhile, only a smaller group experiences covered losses.
When a covered loss occurs, the pool provides financial support to that policyholder.
Why Many Contributions Matter
The pool depends on contributions from many policyholders.
Because fewer policyholders experience covered losses, collected premiums can support those claims.
Therefore, each policyholder shares part of the broader financial risk.
This structure makes protection possible without requiring anyone to pay the full loss alone.
The Math Behind Shared Risk
The basic calculation compares total premiums with covered financial support.
Many policyholders contribute smaller amounts toward the shared pool.
Then, a smaller group receives support when covered losses occur.
As a result, insurance distributes potential costs across the pool.
What Policyholders Receive
Policyholders do not receive support simply because they contribute premiums.
Instead, covered losses determine when the pool provides financial assistance.
This distinction shows why the arrangement depends on contributions and covered events.
Your Personalized Financial Plan
Get expert financial advice tailored exclusively to your goals. Receive a custom roadmap in just 1-3 business days.
Get StartedUltimately, risk pooling connects premium payments with shared financial protection.
Seeing Insurance Through Expected Value
Expected-value thinking compares a certain premium with protection against an uncertain loss.
The policyholder pays the premium whether or not a covered event occurs.
However, that payment purchases financial protection when a covered loss creates serious costs.
Value Exists Without a Claim
A policyholder may never file a claim and still receive meaningful value.
The policy transfers responsibility for a potentially severe covered loss.
Therefore, the policyholder gains protection rather than a guaranteed financial return.
This protection can justify the premium even when the policyholder receives no claim payment.
Comparing Certain Costs With Uncertain Losses
The premium creates a known cost that the policyholder can consider in advance.
Meanwhile, a covered loss creates an uncertain cost that may substantially exceed the premium.
Expected-value thinking recognizes both possibilities instead of judging insurance by claims alone.
Consequently, avoiding a severe financial setback can represent the policy’s central value.
Why a Claim Is Not the Only Measure
A claim measures whether a covered event occurred.
However, it does not fully measure the protection available before that event.
Unlock a Debt-Free Future with Our Unique Strategies
Imagine a life unburdened by debt—a reality we help you visualize and achieve. We offer personalized strategies tailored to your unique situation, guiding you step-by-step toward financial freedom.
Start TodayMoreover, insurance reduces exposure to a loss that could create serious financial consequences.
Thus, a policy can serve its purpose even when the policyholder never uses its claims process.
The Premium Provides Budget Stability
A premium creates a known expense for your financial planning.
You pay that amount according to the policy’s terms.
Therefore, you can anticipate this cost more easily than an unexpected financial setback.
Losses Can Vary in Timing and Size
Illness, accidents, property damage, and lost income can create uncertain financial pressure.
You may not know when an event will occur.
Moreover, you may struggle to predict the event’s total cost.
This uncertainty can make sudden expenses harder to manage.
Different Events Create Different Pressures
Illness can affect finances through expenses connected with the situation.
Meanwhile, accidents can create costs and disrupt normal financial plans.
Property damage can require resources before you expect to need them.
Additionally, lost income can reduce money available for regular obligations.
Each event can affect your finances differently.
Unlock Untapped Nigerian Wealth with Our Expert Advice
Imagine accessing investment opportunities others overlook—stocks, bonds, real estate, small businesses tailored to you. We offer personalized advice you won't find elsewhere, guiding you to financial success.
Unlock WealthInsurance Changes the Financial Tradeoff
Insurance exchanges a predictable premium for protection against an uncertain covered loss.
This arrangement can make financial planning more manageable.
Instead of facing an unknown financial impact, you account for a known premium.
However, policy terms determine which losses receive support.
Therefore, you should compare the premium with the risks the policy addresses.
Predictability Has Practical Value
A predictable payment can help you organize spending before an unexpected event occurs.
Meanwhile, an uncertain loss can force difficult financial decisions at an inconvenient time.
Insurance does not remove every financial concern.
Nevertheless, it can make certain risks easier to anticipate financially.
That predictability shows how insurance can support financial planning.
Gain More Insights: What Insurance Really Buys: Peace, Not Payouts
How Insurers Build a Sustainable Premium
Insurance pricing follows a financial structure rather than relying on hidden tricks.
Insurers must collect enough premium revenue to support their obligations and remain financially viable.
This structure connects premium collection with the obligations insurers must meet.
Covering Expected Claims
Expected claims represent the payments insurers anticipate making for covered losses.
Insurers include these anticipated payments when setting premium levels.
Therefore, premiums must reflect the claims costs associated with the coverage provided.
Paying Operating Costs
Insurers also face operating costs while managing policies and claims.
These costs may include policy administration and claims processing.
Consequently, premiums must cover more than claim payments alone.
Maintaining Reserves
Insurers set aside reserves to support future obligations.
Reserves help insurers prepare for claims that arise after customers pay premiums.
Thus, insurers must account for future responsibilities when pricing coverage today.
Including a Reasonable Margin
Insurers also include a reasonable margin within their pricing.
This margin supports continued operation after claims, costs, and reserves receive funding.
However, a margin does not replace legitimate financial obligations.
Seeing the Complete Equation
A sustainable premium combines expected claims, operating costs, reserves, and a reasonable margin.
Each component serves a distinct purpose within the insurer’s financial model.
When premiums support these components, profitability can result without cheating policyholders.
Therefore, insurance profitability reflects disciplined pricing rather than evidence of a scam.
Uncover the Details: Why Early Coverage Costs Less and Protects More
How Policy Terms Change the Mathematics
Policy terms determine when coverage applies and how much financial support the policy provides.
Therefore, reading each term helps you evaluate the policy’s actual protection.
These terms define the conditions and limits that shape payment.
Deductibles Create Shared Costs
A deductible represents the amount the policyholder pays before coverage contributes toward a covered loss.
Therefore, a higher deductible usually shifts more initial cost to the policyholder.
A lower deductible usually shifts less initial cost to the policyholder.
However, the deductible does not necessarily apply to every situation in the same way.
The policy wording explains when and how the deductible affects payment.
Consequently, compare the deductible with your available resources for an unexpected covered loss.
Coverage Limits Set the Maximum Payment
A coverage limit sets the maximum amount the policy can pay for a covered loss.
Therefore, a policy can provide coverage while still leaving some costs unpaid.
The policy may also apply different limits to different types of covered losses.
Accordingly, examine each limit instead of relying only on the general coverage description.
A limit matters most when the covered financial impact exceeds the available protection.
Exclusions Define What Coverage Does Not Include
Exclusions identify situations, losses, or conditions that the policy does not cover.
Therefore, a policy’s coverage cannot be understood by reading covered events alone.
Exclusions reduce the range of situations in which the policy can provide payment.
Consequently, review exclusions alongside coverage descriptions and definitions.
Words that seem similar can carry different meanings within the policy.
Careful reading helps distinguish covered circumstances from excluded circumstances.
Waiting Periods Delay Eligibility
A waiting period delays when coverage or benefits can begin.
Therefore, a policy may exist before it provides financial support for a particular situation.
The waiting period changes the timing of protection, not necessarily the stated coverage limit.
Consequently, identify when the waiting period starts and when eligibility begins.
That timing matters because financial needs can arise before coverage becomes available.
Reading Terms as a Mathematical Checklist
Evaluate a policy by connecting its terms to the financial situation it addresses.
First, identify the covered event and the conditions that trigger payment.
Next, determine the applicable deductible and subtract it from the covered loss.
Then, apply the relevant coverage limit to the remaining covered amount.
Afterward, check whether an exclusion removes the event or cost from coverage.
Finally, confirm whether a waiting period delays eligibility for payment.
This process reveals the difference between stated coverage and usable protection.
Questions That Clarify the Policy
- Which events does the policy cover?
- Which events or costs does the policy exclude?
- What deductible applies to the covered loss?
- What coverage limit applies to the situation?
- Does a waiting period delay eligibility?
- Which policy definitions control these answers?
Clear answers make the policy’s financial mechanics easier to understand.
The terms show what protection the policy promises under defined conditions.
You Might Also Like: How Insurance Helps You Avoid Turning Emergencies Into Debt
Insurance Has a Different Purpose
Insurance primarily transfers financial risk from the policyholder to the insurer.
Therefore, insurance protects finances instead of creating guaranteed profit.
The policyholder pays for defined protection under specific contractual terms.
Protection Instead of Profit
In return, the insurer accepts responsibility for covered losses.
However, insurance does not guarantee a financial gain for the policyholder.
Instead, the policy provides support when covered events create financial harm.
Why Premium Recovery Is Not the Goal
A policy does not promise to return every premium payment.
Instead, premiums purchase access to financial protection during covered events.
Consequently, a claim-free policy can still provide meaningful value.
The protection remains useful even when the insured event never occurs.
Different Measures of Value
An investment typically focuses on growth, income, or eventual value.
Insurance focuses on reducing the financial consequences of uncertain events.
Therefore, comparing premiums directly with investment returns can create confusion.
The better question asks which financial risk the policy transfers.
It also asks whether the coverage matches the policyholder’s protection needs.
Understanding the Policyholder’s Trade-Off
The policyholder accepts a certain cost for protection against uncertain financial harm.
This trade-off can make sense without producing a financial gain.
However, the policyholder should understand exactly what the contract protects.
Clear expectations help distinguish useful coverage from an unsuitable purchase.
A More Accurate Way to Judge Insurance
Evaluate insurance by its protection, terms, and fit for personal circumstances.
Do not judge the policy solely by whether it returns money.
Likewise, do not treat a claim payment as investment income.
A claim addresses a covered loss according to the policy’s conditions.
Ultimately, insurance supports financial resilience rather than guaranteed financial growth.
Gain More Insights: Understanding the Role of Trust in Choosing Insurance Providers
Self-Insurance as a Mathematical Alternative
Self-insurance means accepting financial responsibility instead of transferring that responsibility through insurance.
However, this choice requires more than confidence in personal savings.
You must assess whether your available funds can absorb the entire uncovered loss.
Measuring the Full Financial Exposure
Start by identifying the total cost you would personally face after an uncovered event.
Do not measure only the amount you expect to pay immediately.
Instead, include every financial obligation that the loss could create.
Then compare that total exposure with funds you can access without creating another financial problem.
This comparison reveals whether self-insurance can realistically absorb the loss.
Separating Available Funds from Intended Savings
Money set aside for other purposes may not provide reliable protection against an uncovered loss.
Therefore, distinguish accessible emergency funds from savings serving essential future needs.
Self-insurance requires funds that remain available when the loss occurs.
If using those funds would undermine essential obligations, your savings may not provide sufficient protection.
Testing the Worst Reasonable Outcome
Evaluate the largest uncovered loss you could realistically face.
Next, determine whether your savings could cover that loss without requiring immediate replacement.
Also consider whether another financial demand could arise before you rebuild those funds.
This approach tests your actual capacity rather than your general willingness to accept risk.
Considering Recovery After a Loss
Self-insurance does not end when savings cover the initial expense.
You must also consider how quickly you could restore the funds you used.
Meanwhile, depleted savings could leave you exposed to another uncovered loss.
Therefore, assess both the initial payment and the financial recovery process.
Using a Clear Decision Standard
Insurance may deserve consideration when the full loss exceeds your realistic financial capacity.
Self-insurance may appear more practical when available savings can absorb the entire exposure.
However, the decision should reflect actual resources rather than optimism about avoiding losses.
Ultimately, compare the cost of transferring risk with the cost of retaining it yourself.
A Practical Policy Review
Evaluate each policy by connecting its cost with the risks it actually addresses.
First, identify the financial problem the policy would help you manage.
Then, consider whether the policy addresses that problem directly.
This approach helps you compare protection with your financial capacity.
Furthermore, it keeps price from becoming your only decision factor.
Compare the Premium With the Protection
Review the premium as a predictable cost for access to defined protection.
Next, compare that cost with the losses the policy might cover.
A higher premium may provide broader protection, but the added coverage must fit your needs.
Similarly, a lower premium may leave important financial risks outside the policy.
Therefore, judge the premium against the protection rather than viewing price alone.
Examine Covered Risks
List the risks the policy covers before deciding whether the protection seems valuable.
Next, consider whether those risks could create serious financial pressure.
A policy may matter most when it addresses losses that exceed your available resources.
However, coverage only helps when the event matches the policy’s stated terms.
Therefore, compare the covered risks with the financial problems you intend to manage.
Consider Probability and Loss Size
Estimate how likely each covered risk appears within your circumstances.
Then, consider the potential size of the resulting loss.
A less likely event can still deserve attention when its financial impact could become severe.
Conversely, a frequent event may matter less when each loss remains manageable.
Thus, review probability and potential loss together instead of considering either factor alone.
Check Exclusions and Coverage Boundaries
Read the exclusions because they identify situations the policy does not cover.
Also, review coverage limits because they restrict the amount the policy can pay.
Check conditions that could affect whether a covered loss qualifies for payment.
These boundaries determine how much protection remains after the policy’s general description.
Therefore, compare the excluded risks with the risks you intended to address.
Test Affordability
Assess whether the premium fits comfortably within your ongoing budget.
Next, consider whether you could maintain the policy without creating new financial strain.
Affordable protection should remain manageable while still addressing meaningful risks.
If the premium creates pressure, examine whether different coverage choices better match your resources.
However, avoid judging affordability only by the premium’s immediate size.
Also, consider the financial consequences of facing an uncovered or insufficiently covered loss.
Use a Consistent Decision Process
Write down the premium, covered risks, estimated probability, potential loss size, exclusions, and affordability.
Then, compare those factors using the same questions for each policy.
- What loss does this policy address?
- How likely does that loss appear?
- How large could the loss become?
- Which exclusions or limits could reduce protection?
- Can the premium remain affordable over time?
Finally, choose protection based on the overall fit between cost, risk, and financial capacity.
This framework turns insurance evaluation into a structured comparison rather than a reaction to price alone.
Additional Resources
Google search results for Why Insurance Isn’t a Scam When You Understand the Math Insurance
Bing search results for Why Insurance Isn’t a Scam When You Understand the Math Insurance